Financial literacy of children from the earliest age
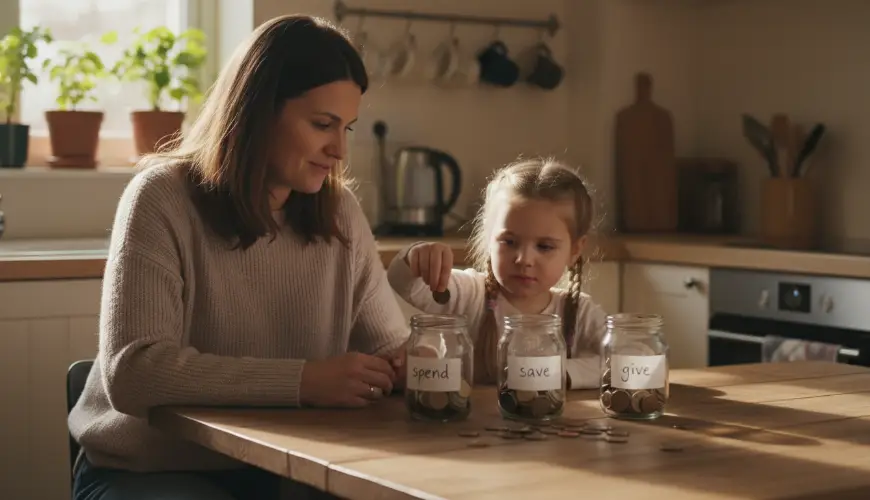
Money is one of the most common sources of stress in adult life, yet it receives surprisingly little attention in upbringing. Most parents agree that financial literacy is important, but when it comes to an actual conversation at the dinner table, the topic somehow disappears on its own. Yet it is precisely at home, in everyday situations, that the foundations are laid for how a person will handle money throughout their entire life.
Research repeatedly shows that financial habits form much earlier than most parents would expect. According to a University of Cambridge study, basic attitudes towards money are largely formed by the age of seven. This doesn't mean that a preschooler should understand an investment portfolio, but it certainly means that waiting until secondary school to have conversations about finances is too late.
The good news is that talking to children about money doesn't have to be rocket science. It's enough to know what a child can understand at a given age and to adapt the way the topic is introduced accordingly.
Try our natural products
Young children and first steps: a world of coins and decisions
With the youngest children, roughly between the ages of three and six, the main goal is for them to understand that money is not a magical thing that comes out of an ATM whenever needed. At this age, children think concretely and in the present tense, so abstract concepts like "saving for the future" or "family budget" make no sense. What does make sense is direct experience.
A simple real-life example: a parent takes a child to a shop and puts some coins in their hand. The child can choose one small sweet or toy. This teaches them that money gets you things, but also that one choice excludes another. This basic understanding of compromise and choice is the first building block of financial intelligence.
At this age, transparent piggy banks or jars work wonderfully, allowing the child to see coins accumulating. The physical presence of money is essential for a young child – a card or mobile payment simply carries no real weight for them. Parents can introduce a simple system of three jars: one for spending, one for saving, and one for giving. This approach, popularised by American financial educator Ron Lieror, teaches children from an early age that money has different purposes and that it can be managed consciously.
Conversations at this age should be short, playful, and tied to a specific situation. There's no need to explain how the economy works – it's enough to say: "Do you see that toy? It costs as much as you have in your hand right now. Do you want to buy it, or would you like to save the money?" The child thus experiences real decision-making, not just theory.
It is also important not to underestimate the influence of one's own behaviour. Children at this age are observers par excellence. If they see their parents buying things mindlessly, or conversely carefully comparing prices, they absorb these patterns long before they are capable of thinking about them.
School age: pocket money, chores, and understanding value
Between the ages of seven and twelve, a whole new world of possibilities opens up for children in terms of financial education. Thinking becomes more logical, the child understands time and can imagine saving up for something. This is where pocket money comes in as one of the most effective tools parents have at their disposal.
The debate about whether to tie pocket money to household chores or give it unconditionally has no single correct answer. Each approach has its pros and cons. Conditional pocket money teaches that money is a reward for work – which reflects the reality of the adult world. On the other hand, unconditional pocket money gives the child space to learn to manage money without pressure and to understand that household chores are part of family life, not a business transaction. Many child psychology experts recommend a combination: basic pocket money with no conditions and the opportunity to earn extra for exceptional tasks.
Whatever approach parents choose, the key is to give the child genuine autonomy in deciding how to spend their pocket money. If a parent constantly intervenes and comments on every purchase, the child won't learn responsibility – they'll only learn how to avoid criticism. Letting a child buy something unnecessary and then complain about it is a valuable lesson that no conversation can fully replace.
This is also the right age to start talking about the value of things in a broader context. How was that jumper the child wants to buy made? Who made it and under what conditions? These topics naturally connect financial literacy with values such as fair trade, sustainability, or ethical consumption – and school-age children are surprisingly open to such topics. It's not about moralising, but about broadening the perspective: money is not just numbers, it's decisions that have consequences.
A clever way to open up these topics is shopping together – whether for clothes, toys, or food. Comparing prices, reading ingredients, looking for alternatives: these are all practical skills that a child learns naturally in a real context. And if the family consciously chooses environmentally friendly products or locally made goods, it's a great opportunity to explain why it's sometimes worth paying more for something of higher quality or greater ethical value.
As Warren Buffett once said: "The sooner you learn to save and invest, the better off you'll be." This idea applies in the children's world too, albeit on a much more modest scale – a schoolchild who sets aside part of their pocket money for something they've been dreaming of is experiencing, in miniature, exactly the principle Buffett describes.
Adolescence: time for real financial education
Teenagers are on the threshold of adulthood and their financial decisions are beginning to have real consequences. A part-time job, their own bank account, first major purchases – all of this brings new challenges and opportunities. And this is precisely where many parents either stop talking about money altogether (because the teenager "surely knows by now"), or conversely launch into lectures that put adolescents off any discussion.
An effective approach is different: instead of lectures, involve the teenager in the family's real financial decisions. Not so that they bear responsibility for the family's finances, but so that they can see how things work in practice. How much does electricity cost? How is a family budget put together? What does a mortgage mean? These conversations don't need to be formal – they can naturally arise from everyday situations.
Having their own bank account is an important milestone for a teenager. Managing their own money, tracking expenses, and planning ahead are skills that cannot be learned from a book – they have to be experienced. Parents can help set basic rules and offer support, but excessive control undermines this process.
At this age, it is also appropriate to open up topics such as credit cards, loans, and interest rates. Many young people run into financial difficulties precisely because they never understood how debt works. Explaining with a simple example what it means to borrow money with interest is an investment in a child's future that pays back many times over.
Interestingly, OECD studies on youth financial literacy repeatedly show that young people who talked about finances at home with their parents achieve significantly better results in managing money as adults. School may provide the theory, but family provides the context and values that are equally important.
Adolescents also begin to perceive consumer culture more critically – or conversely slide into it under peer pressure. Conversations about advertising, about how marketing works and why certain things tempt us to buy, are enormously valuable at this age. Teaching a teenager to distinguish between what they genuinely want and what someone is trying to sell them is one of the most important things parents can pass on.
Financial education is not a one-off conversation, but a long-term process that adapts as the child grows. There's no need to be a financial expert or to have one's own finances perfectly sorted – it's enough to be willing to speak openly, make mistakes, and learn from them together. Children who see their parents thinking about money consciously and thoughtfully naturally adopt this approach. And that is a foundation on which an entire life can be built.